Rat-infested property is “suitable for use as a dwelling”
The First-tier Tribunal has found that a property in disrepair, inhabited by rodents, is still suitable for use as a dwelling for tax purposes. This sounds illogical - so what’s the full story?
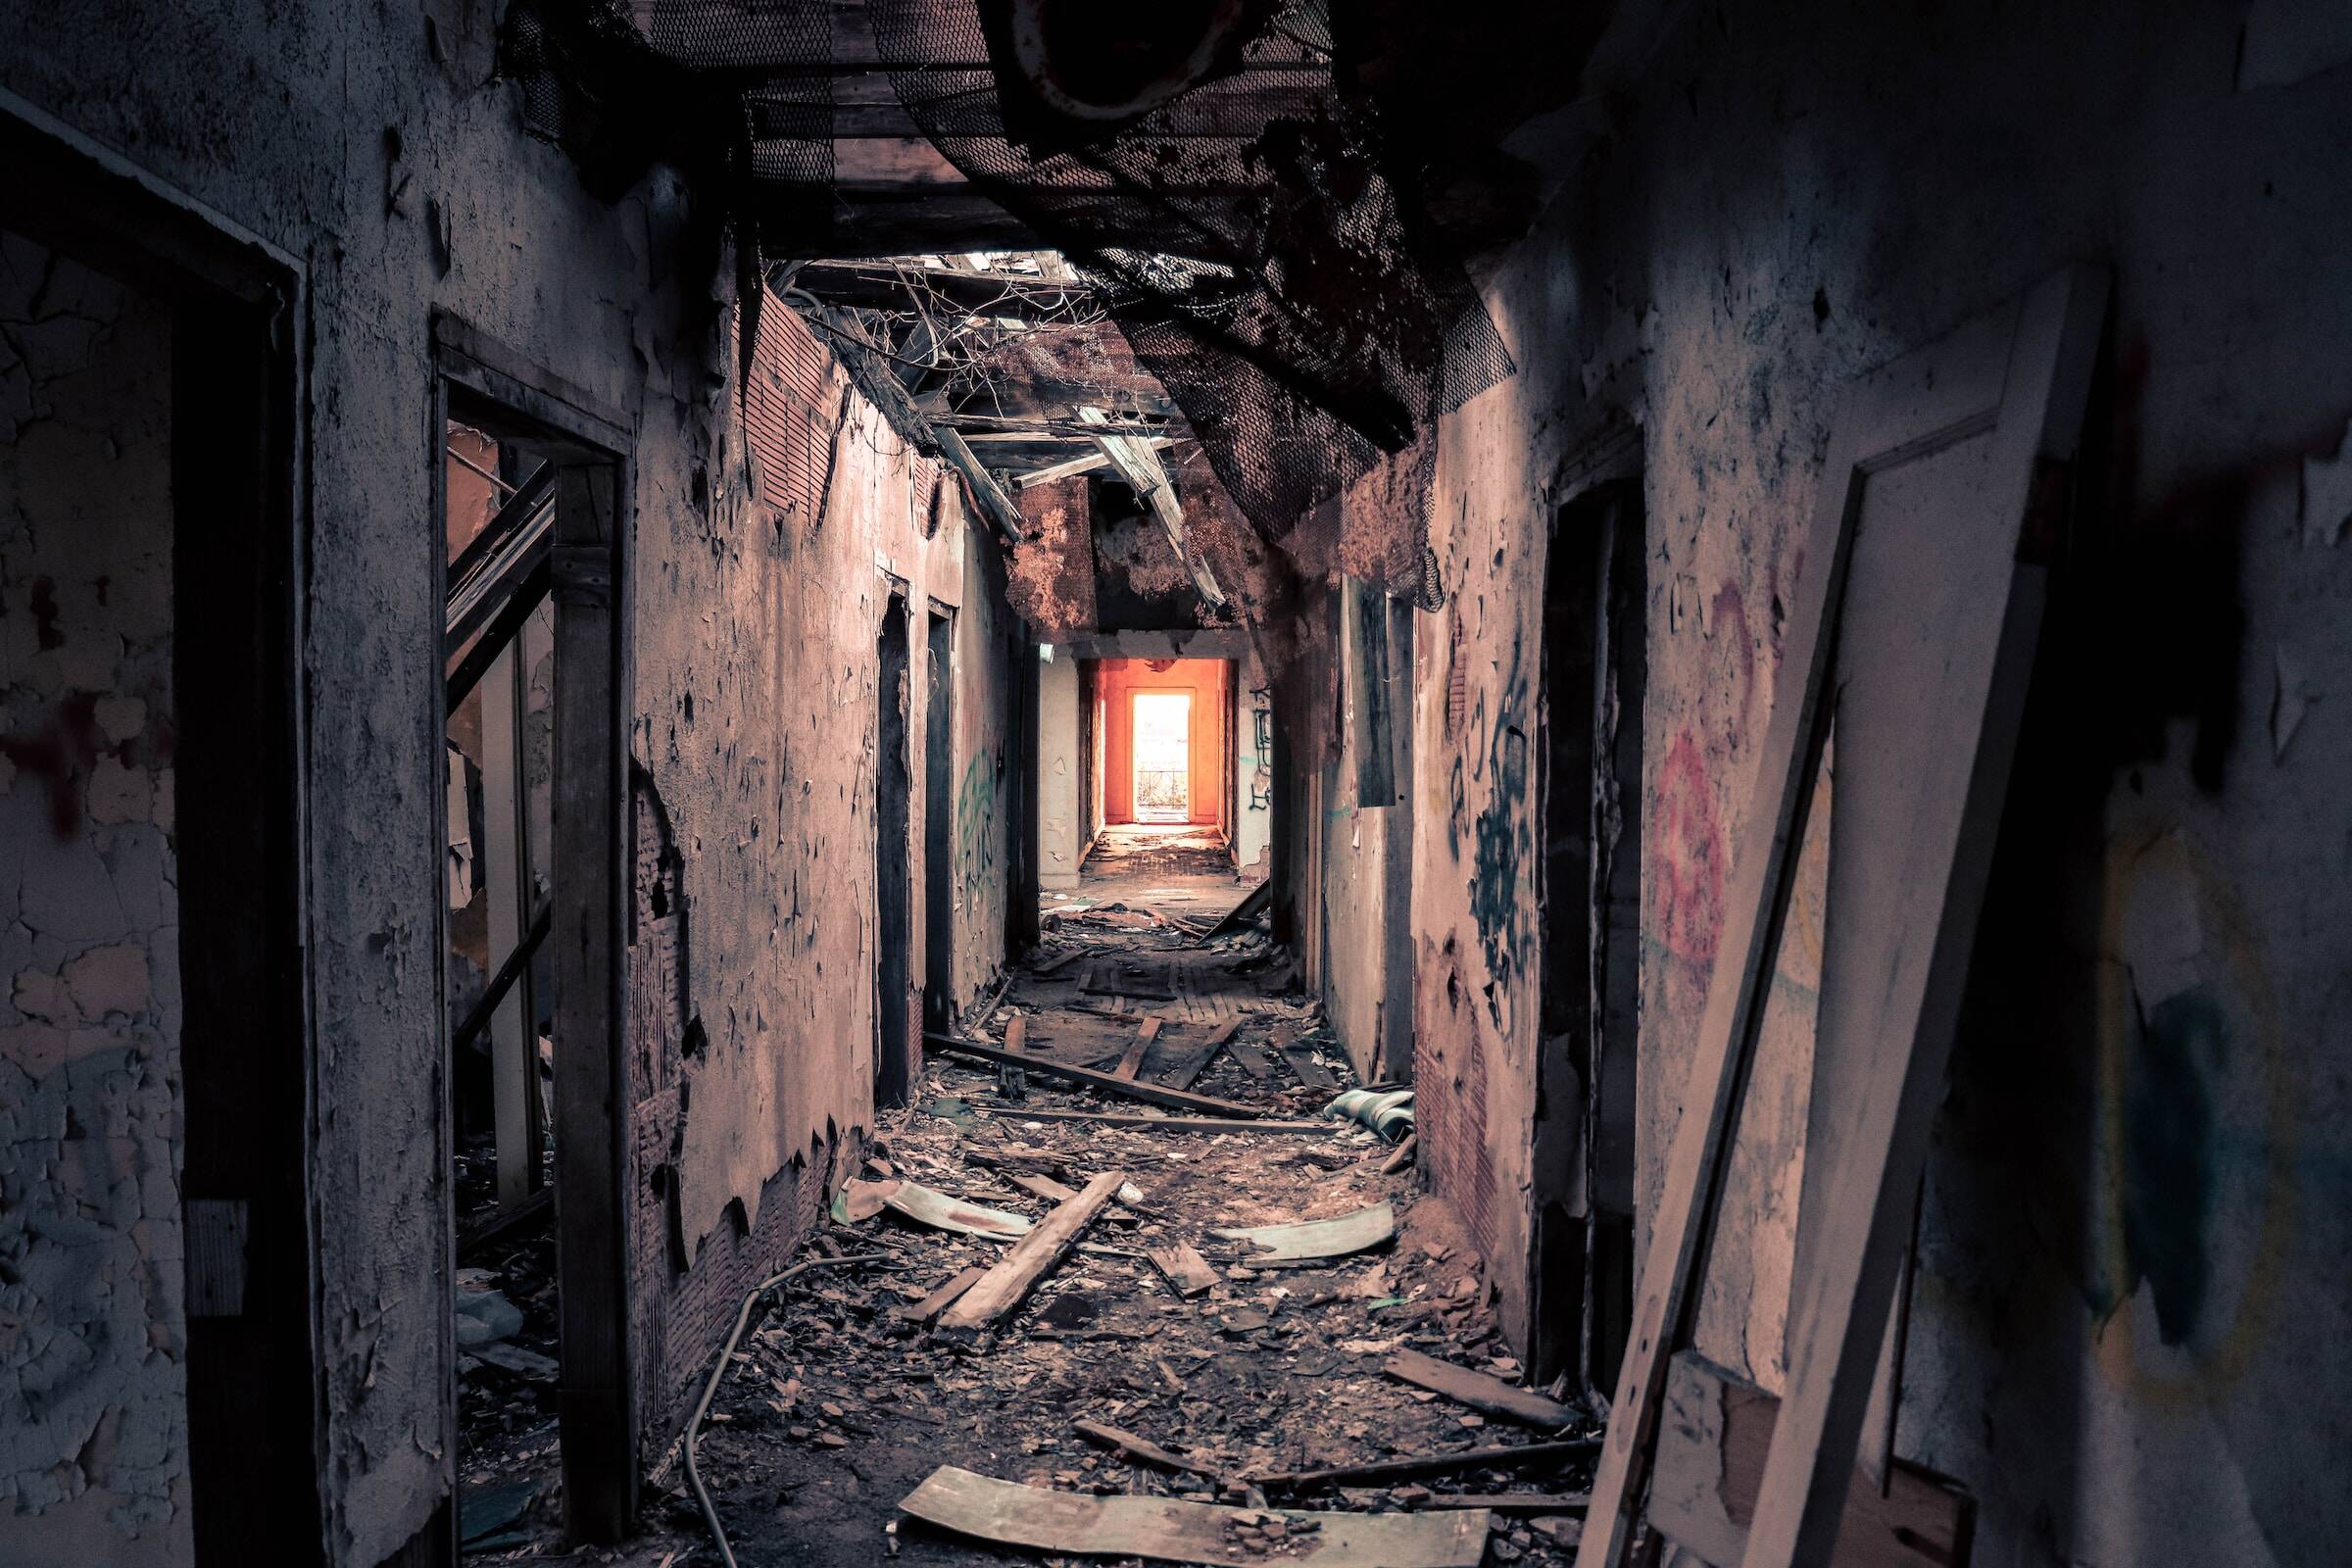
In Mudan & Anor v HMRC the taxpayers (the Ms) purchased a £1.7m property in London that had been empty for five months after the previous tenants were evicted. During that time, the property had been broken into and vandalised, none of the utilities worked and mice and rat droppings covered the kitchen. The boiler had been ripped off the wall, the gas, electricity and water were not functioning safely and rainwater was leaking into the property. It took nine months of renovations before the Ms moved into the property.
Higher rates of stamp duty land tax (SDLT) are chargeable on residential properties, with the pertinent part of the definition being that the property is residential if it is “suitable for use as a dwelling”. Due to the state of the property, the Ms argued that it was not suitable to be occupied and so lower rates of SDLT should apply. HMRC, and ultimately, the tribunal disagreed. The judge confirmed that the bar for a property not to be suitable for use as a dwelling was set very high, and that a building which was recently used as a dwelling, has not in the interim been adapted for another use, and is capable of being so used again will count as a dwelling for SDLT purposes. An additional £100,000 SDLT was due on the purchase, and the appeal was dismissed.
Related Topics
-
HMRC moves tax return registration into the digital age
A new and improved self-assessment registration service has been launched. What's changed?
-
Unpaid directors still face new tax return reporting
HMRC has clarified that company directors who are already required to submit a self-assessment tax return must provide details of their directorships for 2025/26 even where they received no salary, benefits or dividends. Directors of dormant companies can also be caught. What do you need to know?
-
Do dividend waivers still work?
You need to take a dividend from your company but there’s just one problem. Your business partner, who is also a 50% shareholder, doesn’t want to take any more income from the company during this tax year. What’s the solution?